Will my lender approve a short sale on my Far Rockaway house?
Most do, especially when there's hardship documentation and a cash buyer ready to close. Tony's title company has worked with dozens of NJ and NY lenders and knows what each requires.
If you owe more on your Queens County mortgage than the house is worth, Tony's short-sale process gets the lender to accept Tony's cash offer as full satisfaction. You walk away with no continuing debt. No deficiency. No long-term credit damage from foreclosure.
Being underwater on a house is one of the most demoralizing financial situations a homeowner can face. You're working to keep paying for something that's worth less than what you owe. Walking away feels like surrender, but staying feels like throwing money into a hole. A short sale is the cleanest exit — and Tony has done dozens of them across NJ and NY.
Queens County short sales used to take 6-12 months. With Tony's experience and a motivated cash offer on the table, most close in 60-90 days. Faster than waiting for foreclosure, much cleaner than foreclosure on your credit.
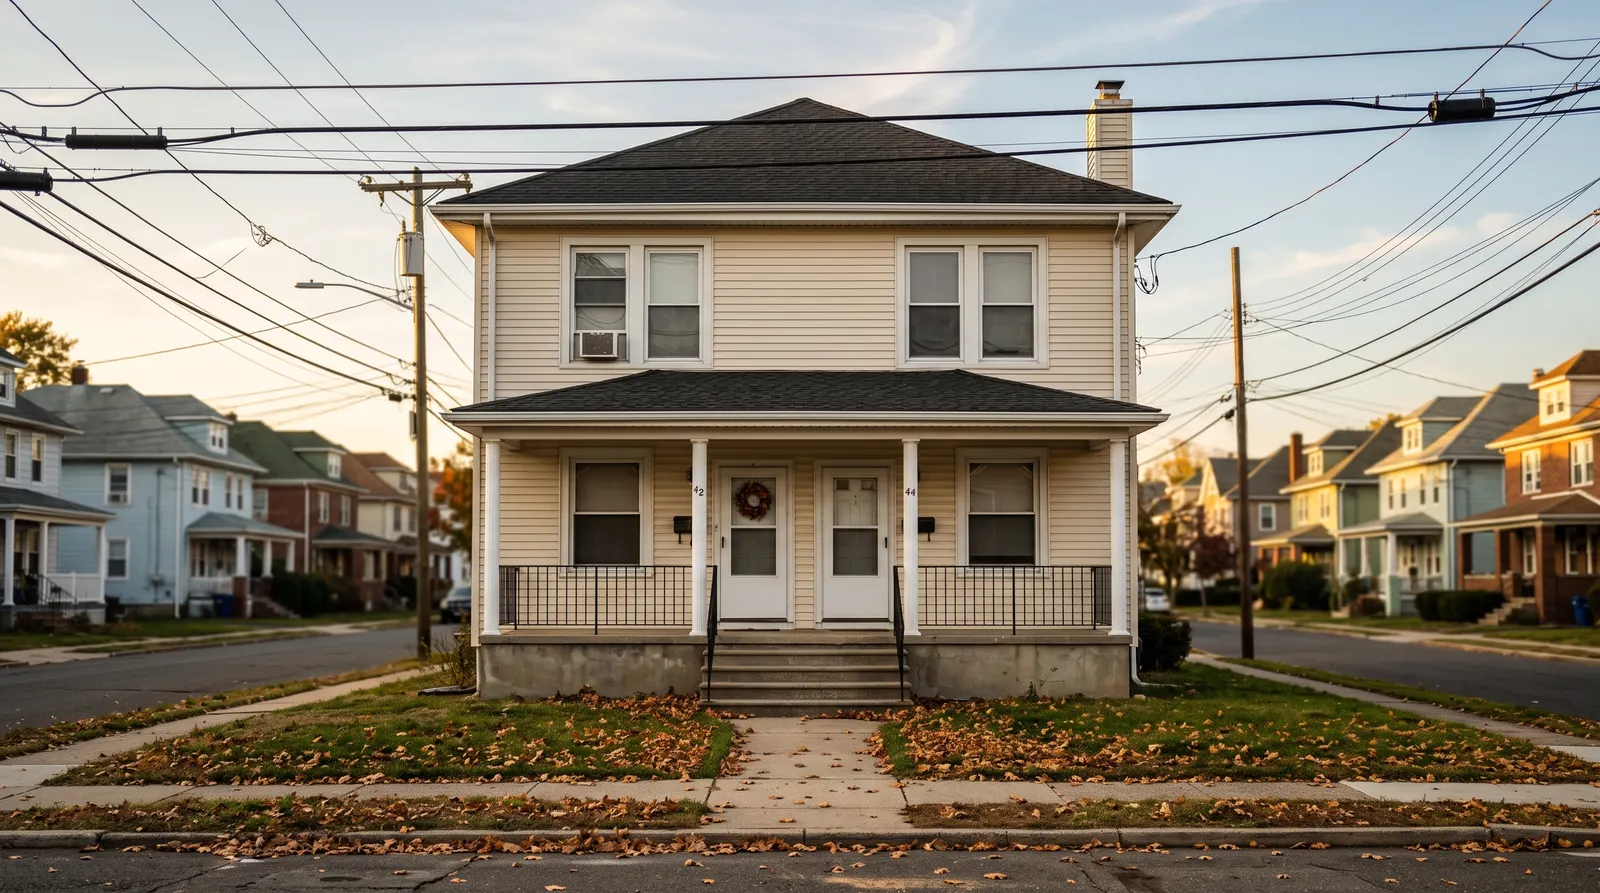
The kind of two family property Tony has bought in Far Rockaway.
Queens County has detached single-families and two-families across south Queens (Jamaica, Hollis, St. Albans, Cambria Heights, Laurelton, Rosedale). Many are inherited from grandparents who immigrated in the 1950s-70s.
Queens NYC Class 1 rates apply; effective rates are 0.7-1.4% on actual market value due to assessment caps.
§·· / Schedule
Tell Tony where the house is and what shape it's in. Get a cash number on the same call. Pick a closing date.
7 days a week, 8 AM to 9 PM Eastern.
Here's how a Queens County short sale works with Tony. Tony makes a cash offer. You sign a short-sale package authorizing Tony's title company to negotiate with your lender on your behalf. The lender reviews, approves the lower payoff, and the closing happens 60-90 days out. At closing, the lender accepts Tony's payment as full satisfaction; you have no remaining mortgage obligation.
Far Rockaway is detached frame one- and two-families and 1920s bungalows in Edgemere and Arverne, larger houses and an Orthodox Jewish community around Central Avenue and Bayswater, six-story buildings and NYCHA's Redfern and Ocean Bay developments, and the post-2000 Arverne by the Sea townhouses. Nearly all of it is within a FEMA flood zone, and much of it was under water in Sandy in 2012; houses that were raised or rebuilt sit next to ones that were only patched.
Far Rockaway owners call Tony with houses that Sandy never really let go of: a bungalow in Edgemere that was gutted, dried out, and left; a two-family in Arverne with a Build It Back elevation that was started and abandoned; a parent's house in Bayswater whose flood insurance premium now costs more than the taxes. Some are heirs to a frame house in Wavecrest with a tenant paying nothing and a City lien-sale notice on the mailbox. Tony buys them as-is, flood zone and all, with no elevation certificate and no insurance requirement, and gives one number on the phone.
Far Rockaway sellers pay the NYC RPTT (1% up to $500,000, 1.425% above) and the 0.4% NYS transfer tax; Tony nets both. Almost every Far Rockaway property is in a Special Flood Hazard Area, so a mortgage buyer must carry flood insurance and a lender wants an elevation certificate — cash removes both. Sandy-era grants (Build It Back, SBA) sometimes leave a lien or a compliance covenant on title; Tony's title company clears them at closing.
Every cash buyer, Tony included, starts from the same three numbers: what the house would sell for fully renovated, what it costs to get it there, and how long that takes. The offer is that finished value minus the repairs, minus the buyer's resale costs and margin. In practice that lands most cash offers somewhere around 70–85% of the renovated value, less repairs. The honest comparison is not against a renovated house's list price — it is against what you would actually net from a NY listing after commission, repairs, and months of carrying costs.
| Line item | List with an agent | Sell to Tony |
|---|---|---|
| What the house would sell for fully renovated | $400,000 | $400,000 |
| Repairs a retail buyer's lender will demand | − $45,000 | Tony's problem |
| Agent commission (5–6%) | − $20,000 to $24,000 | $0 |
| Inspection credits, seller closing costs, concessions | − $8,000 to $12,000 | $0 |
| Taxes, insurance, mortgage, utilities while you wait (3–6 months) | − $9,000 to $15,000 | $0 |
| Time to cash in hand | 4 to 7 months | 7 to 14 days |
| What you actually walk away with | ≈ $305,000 to $318,000 | Tony's number, in full, on your date |
Whether Tony's number beats that listing net depends on the house. On a move-in-ready home in a hot NYmarket it usually will not, and Tony will tell you to list. On a house that needs work, has tenants, sits in an estate, or carries violations — the houses retail buyers cannot finance — it is often close, and the seven-day timeline is the difference. Call 1-908-768-4759, get the number, and compare it yourself.
Buying since 2018· every county in New Jersey and New York · no commissions or fees · every closing at a licensed NY title company.
Contact
Drop your number and Tony reaches out about your Far Rockaway property within an hour.
Most do, especially when there's hardship documentation and a cash buyer ready to close. Tony's title company has worked with dozens of NJ and NY lenders and knows what each requires.
60-90 days from offer to closing. The lender's review takes most of the time. Tony's part — the offer, the title work, the closing itself — moves fast.
The short-sale agreement typically includes a deficiency waiver, meaning the lender can't pursue you for the gap between what you owed and what they accepted. This is the single biggest difference vs. foreclosure.
Most lenders don't require it. Hardship documentation (job loss, medical, divorce, death) is usually enough. Earlier is better — you're in a stronger position if you haven't yet missed payments.
Less than foreclosure. Short sales typically drop credit 50-150 points and clear in 2-3 years. Foreclosure drops credit 200-400 points and stays 7 years. Major difference for getting another mortgage later.
Yes. Houses that were gutted and left, raised halfway, or patched with mold behind the walls are the kind Tony buys in Far Rockaway. He doesn't need an elevation certificate, flood insurance, or a finished repair. Tell him what was done and what wasn't, including any Build It Back or SBA history, and he'll give you a number.
Yes — ZIPs 11691 and 11692 in full: bungalows in Edgemere, frames and two-families in Arverne and Wavecrest, larger houses near Central Avenue and in Bayswater, condos and townhouses in Arverne by the Sea, and co-ops on Seagirt Boulevard. Flood zone doesn't change whether he'll buy. One call with the address gets you a number.
Yes. Build It Back and SBA disaster loans often left a lien or a covenant on title that must be satisfied or released at closing. Tony's title company gets the payoff or release, it's handled from the proceeds, and his offer accounts for it. It adds paperwork, not a reason he won't buy.
Selling to Tony ends both. Back taxes and any City lien are paid off from the proceeds at closing, and Tony carries the house afterward — with or without insurance, that's his decision, not a condition on you. He can close in about a week once title is clear, which usually beats waiting for the lien sale or the next premium notice.
Stop bleeding money on a Far Rockaway house worth less than the mortgage. 1-908-768-4759.
§·· / Schedule
Tell Tony where the house is and what shape it's in. Get a cash number on the same call. Pick a closing date.
7 days a week, 8 AM to 9 PM Eastern.
Different situation? Tony also handles these Far Rockaway cases:
← All cash buyer options for Far Rockaway·Queens County·New York