Will my lender approve a short sale on my Queens house?
Most do, especially when there's hardship documentation and a cash buyer ready to close. Tony's title company has worked with dozens of NJ and NY lenders and knows what each requires.
If you owe more on your Queens County mortgage than the house is worth, Tony's short-sale process gets the lender to accept Tony's cash offer as full satisfaction. You walk away with no continuing debt. No deficiency. No long-term credit damage from foreclosure.
Being underwater on a house is one of the most demoralizing financial situations a homeowner can face. You're working to keep paying for something that's worth less than what you owe. Walking away feels like surrender, but staying feels like throwing money into a hole. A short sale is the cleanest exit — and Tony has done dozens of them across NJ and NY.
Tony has closed dozens of Queens County short sales across the housing crash, the Sandy aftermath, and the recent rate-driven equity erosion. Lenders typically prefer short sales to foreclosure because Tony's cash close is faster and more certain.
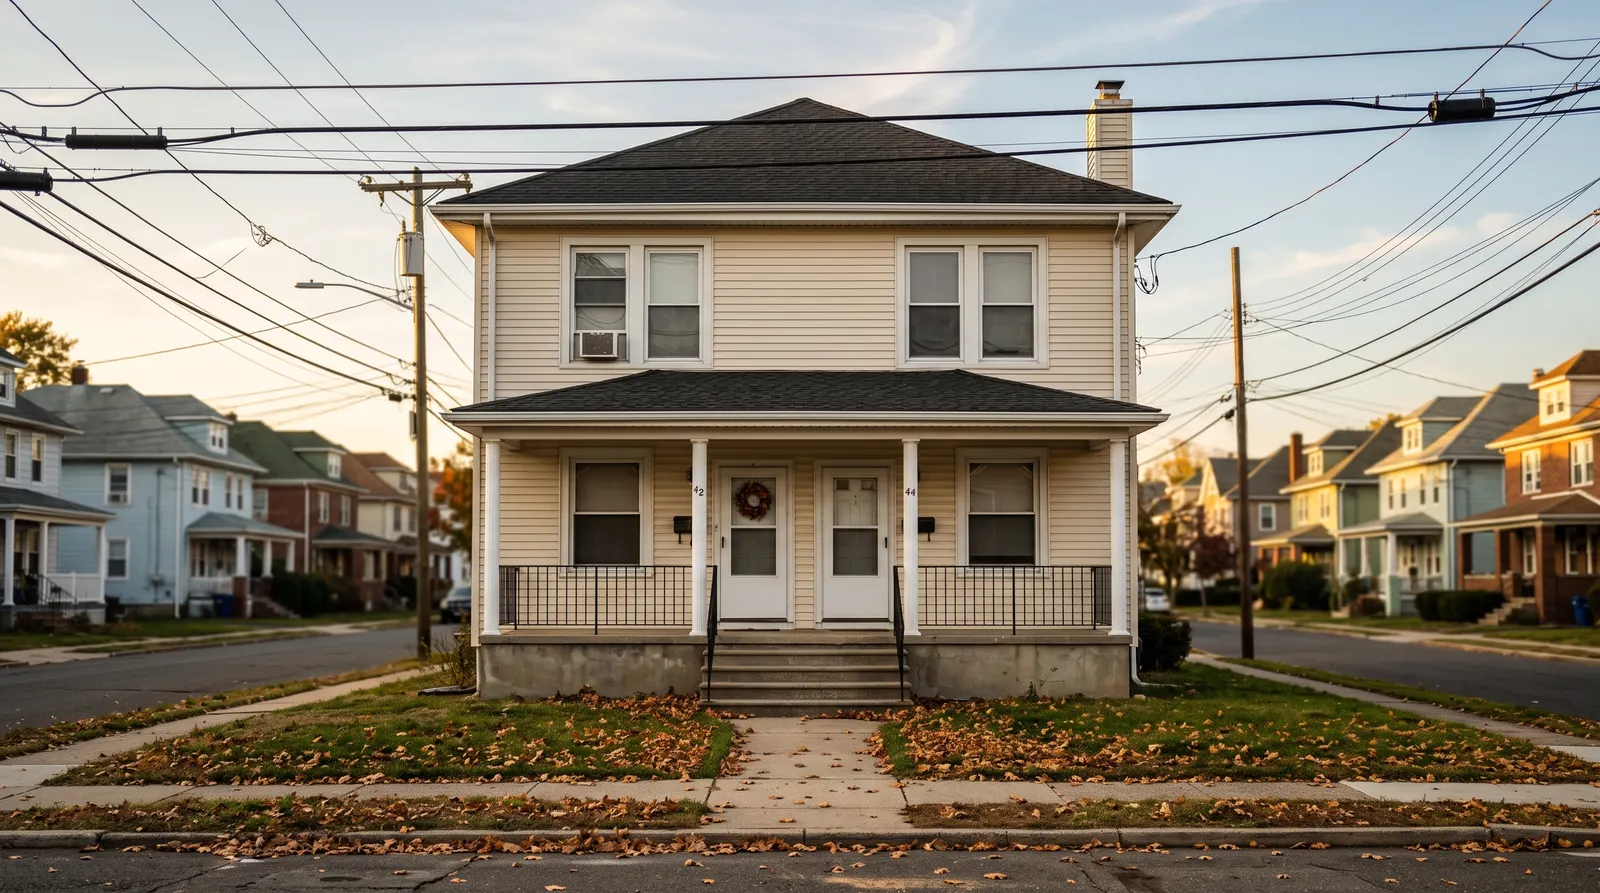
The kind of two family property Tony has bought in Queens.
Queens County has detached single-families and two-families across south Queens (Jamaica, Hollis, St. Albans, Cambria Heights, Laurelton, Rosedale). Many are inherited from grandparents who immigrated in the 1950s-70s.
Queens NYC Class 1 rates apply; effective rates are 0.7-1.4% on actual market value due to assessment caps.
§·· / Schedule
Tell Tony where the house is and what shape it's in. Get a cash number on the same call. Pick a closing date.
7 days a week, 8 AM to 9 PM Eastern.
Queens County short sales benefit you in three ways vs. foreclosure: (1) the credit hit is much smaller — typically 50-150 points vs. 200-400 for foreclosure; (2) you can buy another house in 2-3 years vs. 7+ years after foreclosure; (3) deficiency judgments are typically waived as part of the short-sale agreement, where foreclosure deficiencies can follow you for years.
Queens has detached one-families and two-families across south Queens neighborhoods like Jamaica, Hollis, and St. Albans. Tony buys inherited, distressed, and tenant-occupied properties. Southeast Queens is 1920s–50s detached frames, brick colonials, and Tudors on 40-by-100 lots; western Queens is attached brick two- and three-families and six-story pre-war buildings; the Rockaways mix bungalows, NYCHA, and post-Sandy rebuilds; and co-ops and condos are everywhere from Forest Hills to Flushing.
Queens sellers who call Tony are mostly heirs to a detached house in Jamaica, St. Albans, Hollis, or Laurelton that the family bought in the 1960s or 70s. The deed is in a parent's name, the estate is sitting in Queens County Surrogate's Court on Sutphin Boulevard, and the basement apartment that paid the bills was never legal. Southeast Queens had some of the highest foreclosure rates in the city after 2008, and many of those houses are still being untangled today — reverse mortgages, HUD liens, and second mortgages the heirs didn't know about. Tony buys them as-is, with the tenants, the liens, and the belongings, and gives one number on the phone.
Queens sellers pay the NYC RPTT (1% up to $500,000, 1.425% above) plus the 0.4% NYS transfer tax; Tony's offer is net of both. Queens County Surrogate's Court handles estates for the whole borough, and a reverse mortgage on a deceased parent's house must be paid off at closing before heirs see anything — Tony's title company gets the payoff and his cash closes before the servicer forecloses. Rockaway and Howard Beach properties are in FEMA flood zones, which only matters to a lender.
Every cash buyer, Tony included, starts from the same three numbers: what the house would sell for fully renovated, what it costs to get it there, and how long that takes. The offer is that finished value minus the repairs, minus the buyer's resale costs and margin. In practice that lands most cash offers somewhere around 70–85% of the renovated value, less repairs. The honest comparison is not against a renovated house's list price — it is against what you would actually net from a NY listing after commission, repairs, and months of carrying costs.
| Line item | List with an agent | Sell to Tony |
|---|---|---|
| What the house would sell for fully renovated | $400,000 | $400,000 |
| Repairs a retail buyer's lender will demand | − $45,000 | Tony's problem |
| Agent commission (5–6%) | − $20,000 to $24,000 | $0 |
| Inspection credits, seller closing costs, concessions | − $8,000 to $12,000 | $0 |
| Taxes, insurance, mortgage, utilities while you wait (3–6 months) | − $9,000 to $15,000 | $0 |
| Time to cash in hand | 4 to 7 months | 7 to 14 days |
| What you actually walk away with | ≈ $305,000 to $318,000 | Tony's number, in full, on your date |
Whether Tony's number beats that listing net depends on the house. On a move-in-ready home in a hot NYmarket it usually will not, and Tony will tell you to list. On a house that needs work, has tenants, sits in an estate, or carries violations — the houses retail buyers cannot finance — it is often close, and the seven-day timeline is the difference. Call 1-908-768-4759, get the number, and compare it yourself.
Buying since 2018· every county in New Jersey and New York · no commissions or fees · every closing at a licensed NY title company.
Contact
Drop your number and Tony reaches out about your Queens property within an hour.
Most do, especially when there's hardship documentation and a cash buyer ready to close. Tony's title company has worked with dozens of NJ and NY lenders and knows what each requires.
60-90 days from offer to closing. The lender's review takes most of the time. Tony's part — the offer, the title work, the closing itself — moves fast.
The short-sale agreement typically includes a deficiency waiver, meaning the lender can't pursue you for the gap between what you owed and what they accepted. This is the single biggest difference vs. foreclosure.
Most lenders don't require it. Hardship documentation (job loss, medical, divorce, death) is usually enough. Earlier is better — you're in a stronger position if you haven't yet missed payments.
Less than foreclosure. Short sales typically drop credit 50-150 points and clear in 2-3 years. Foreclosure drops credit 200-400 points and stays 7 years. Major difference for getting another mortgage later.
All of Queens. Most of his volume is in Jamaica, South Jamaica, St. Albans, Hollis, Queens Village, Cambria Heights, Laurelton, Springfield Gardens, and Rosedale, but he also buys in Astoria, Flushing, Jackson Heights, Corona, Ridgewood, Richmond Hill, Ozone Park, and the Rockaways. Detached, attached, two-family, co-op, or condo — one call gets you a number.
Yes, and quickly matters. After the borrower dies, the reverse-mortgage servicer generally gives heirs a limited window before it starts foreclosure. Tony's title company orders the payoff, and his cash closing clears it; whatever equity remains goes to the estate. If the loan balance is close to the value, he'll tell you honestly what's left.
No. Basement and attic conversions without a certificate of occupancy are the norm in Southeast Queens, and Tony buys them with the tenant in place or empty. Any DOB violation or vacate order transfers to him. You don't need to remove the kitchen or pay an expediter before selling.
As soon as Queens County Surrogate's Court issues letters testamentary or letters of administration, Tony can sign a contract and close in about a week. If letters haven't issued, he'll sign and wait — his offer doesn't have an expiration date tied to the court's schedule. His attorney can tell you what the court still needs.
Queens County short sale specialist. 1-908-768-4759. Tony has done dozens.
§·· / Schedule
Tell Tony where the house is and what shape it's in. Get a cash number on the same call. Pick a closing date.
7 days a week, 8 AM to 9 PM Eastern.
Different situation? Tony also handles these Queens cases: