Can Tony close my Long Beach sale before my move date?
Almost always. Tony's standard close is 7-14 days. If you have 30+ days before the move, that's plenty of room.
Moving truck booked? Job start date locked in? Tony closes the Long Beach sale in 7 to 14 days, gives you cash before you leave town, and you don't carry a vacant property from across the country.
Job relocations move on someone else's schedule. The new employer wants you in the office. The lease at the new place starts. The kids' school year matches the move. The house in Long Beach is the one variable you can't control — until it's not. Tony closes faster than any agent can list. Take the cash, take the moving truck, go.
Got a job offer that starts in 30 days and a Long Beach, New York house to sell? Listing with an agent takes 3-6 months. Tony closes in 7-14. Most relocating sellers across Nassau County call Tony specifically because they don't have time for a traditional sale.
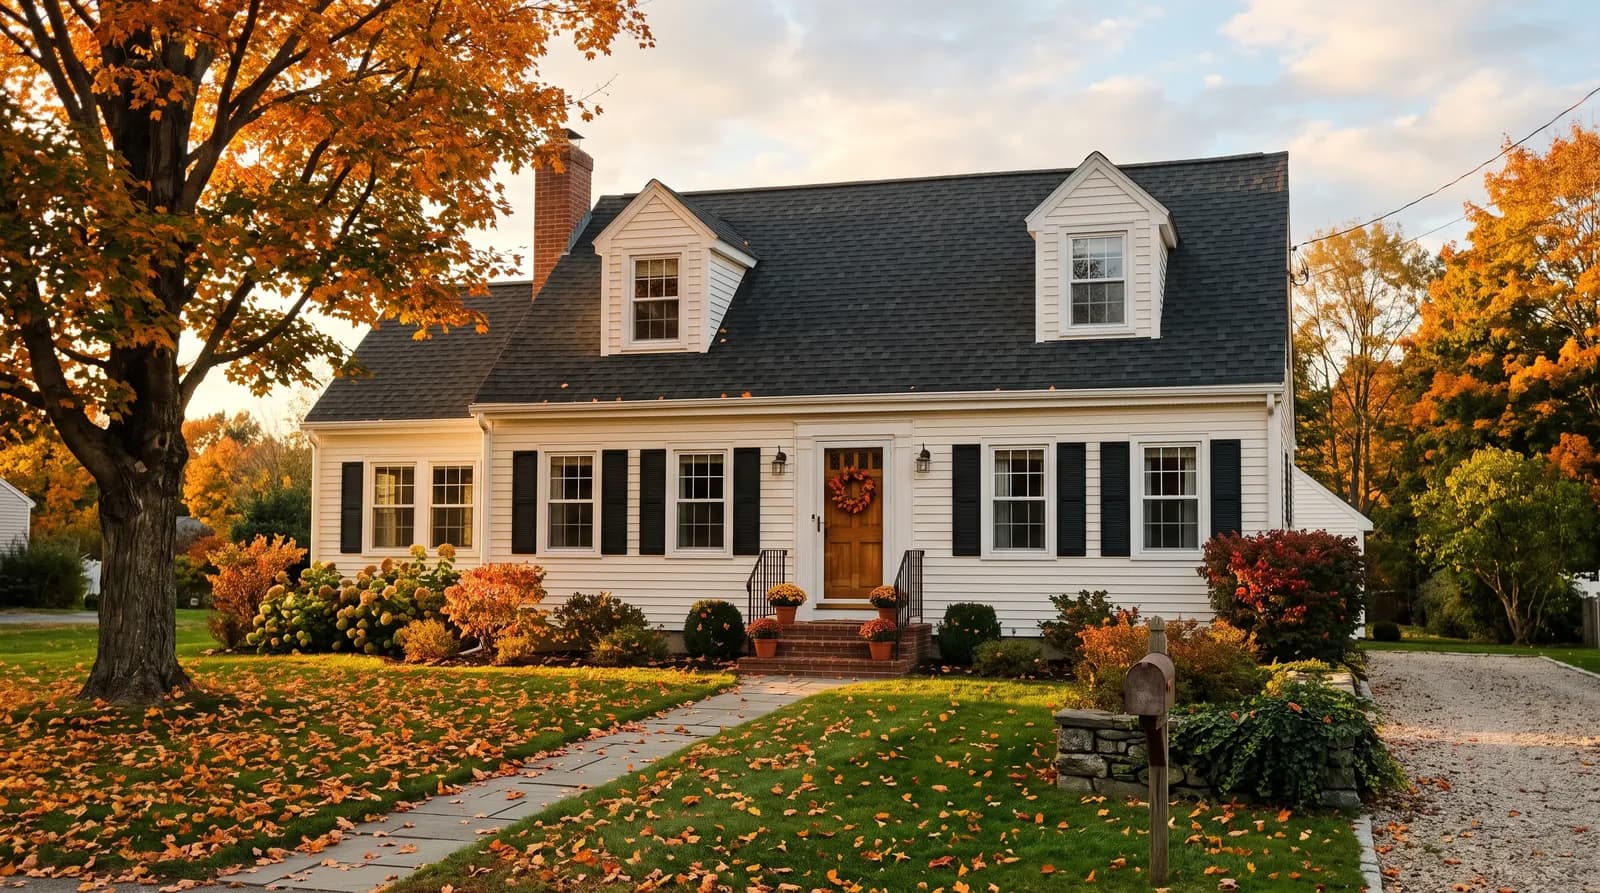
The kind of cape property Tony has bought in Long Beach.
Nassau County is inner Long Island: Hempstead, North Hempstead, Oyster Bay. Levittown ranches, Long Beach co-ops, and Great Neck/Manhasset estates all part of Tony's Nassau pipeline.
Nassau County tax rates are 2.0-2.8%; assessment grievance is common given the elevated rates.
§·· / Schedule
Tell Tony where the house is and what shape it's in. Get a cash number on the same call. Pick a closing date.
7 days a week, 8 AM to 9 PM Eastern.
Some relocating sellers consider renting the Nassau County house out instead of selling. The math rarely works for a remote landlord — repairs from 1,500 miles away cost double, tenants test the boundaries, and the IRS treats the property as a long-term rental for tax purposes. Tony's cash offer eliminates these decisions.
Long Beach is a barrier-island city: 1920s–30s bungalows and small capes on 30- and 40-foot lots in the West End, brick pre-war apartment buildings and co-ops along Broadway and the boardwalk, high-rise co-ops and condos on the ocean, and canal-front and bay-front houses in the East End. The whole island went under water in Sandy in 2012; many houses have since been raised on pilings or new foundations, and many have not. Long Beach runs its own city building department, separate from the Town of Hempstead.
Long Beach owners call Tony about the West End bungalow their parents bought in 1960 that flooded in Sandy, got a NY Rising grant, and never got raised — with insurance premiums now higher than the mortgage. Others are heirs to a boardwalk co-op with a board that takes months, or own a canal house with an elevation started and abandoned when the contractor disappeared. Some are summer-house families who simply don't want to manage a beach house from Manhattan or New Jersey any longer. Tony buys the unraised bungalow, the half-elevated canal house, and the co-op after board approval, with no elevation certificate and no flood insurance required — one number on the phone, closing on your date.
Long Beach sellers pay the 0.4% New York State transfer tax; Tony's offer is net of it. Virtually all of Long Beach is in a FEMA Special Flood Hazard Area, so a mortgage buyer must carry flood insurance and a lender wants an elevation certificate — cash removes both. City of Long Beach building records govern the C of O on raised houses and additions, and NY Rising grants sometimes leave a covenant or lien on title that Tony's title company clears at closing. Deeds record with the Nassau County Clerk in Mineola.
Every cash buyer, Tony included, starts from the same three numbers: what the house would sell for fully renovated, what it costs to get it there, and how long that takes. The offer is that finished value minus the repairs, minus the buyer's resale costs and margin. In practice that lands most cash offers somewhere around 70–85% of the renovated value, less repairs. The honest comparison is not against a renovated house's list price — it is against what you would actually net from a NY listing after commission, repairs, and months of carrying costs.
| Line item | List with an agent | Sell to Tony |
|---|---|---|
| What the house would sell for fully renovated | $400,000 | $400,000 |
| Repairs a retail buyer's lender will demand | − $45,000 | Tony's problem |
| Agent commission (5–6%) | − $20,000 to $24,000 | $0 |
| Inspection credits, seller closing costs, concessions | − $8,000 to $12,000 | $0 |
| Taxes, insurance, mortgage, utilities while you wait (3–6 months) | − $9,000 to $15,000 | $0 |
| Time to cash in hand | 4 to 7 months | 7 to 14 days |
| What you actually walk away with | ≈ $305,000 to $318,000 | Tony's number, in full, on your date |
Whether Tony's number beats that listing net depends on the house. On a move-in-ready home in a hot NYmarket it usually will not, and Tony will tell you to list. On a house that needs work, has tenants, sits in an estate, or carries violations — the houses retail buyers cannot finance — it is often close, and the seven-day timeline is the difference. Call 1-908-768-4759, get the number, and compare it yourself.
Buying since 2018· every county in New Jersey and New York · no commissions or fees · every closing at a licensed NY title company.
Contact
Drop your number and Tony reaches out about your Long Beach property within an hour.
Almost always. Tony's standard close is 7-14 days. If you have 30+ days before the move, that's plenty of room.
No. NJ and NY remote notarization lets you sign from anywhere. Most relocating sellers close from their new state without flying back.
Tony rolls with it. The closing date is set by you, not Tony. As long as you give a few days' notice, Tony reschedules without penalty.
Math rarely works for remote landlords. Repairs cost double, tenant management is hard from far away, and the tax treatment is complicated. Most relocating sellers do better with Tony's cash offer.
Leave it. Tony takes the property with everything inside. Saves you the cross-country move of stuff you don't really need.
Yes. Unraised, partly raised, and patched-but-never-finished Sandy houses are what Tony buys most in Long Beach. He doesn't need an elevation certificate, flood insurance, or a completed repair. Tell him what was done, whether NY Rising was involved, and what's still open with the city building department, and he gives you a number.
Yes — all of ZIP 11561: bungalows and capes in the West End, canal-front houses in the East End, pre-war and high-rise co-ops and condos along the boardwalk and Broadway, and everything in between. Co-ops need board approval, which adds a few weeks. One call with the address gets you a number.
Yes. NY Rising and SBA disaster assistance often left a lien or a covenant requiring the house to be raised or kept insured, and any payoff or release is handled through the title company at closing. Tony's offer accounts for it. It adds paperwork, not a reason he won't buy.
Yes, with a signed power of attorney or letters from Nassau Surrogate's Court if she has passed. Tony submits the board package himself and pays cash. Some Long Beach co-ops restrict investor buyers — he reads the proprietary lease and house rules and tells you on the phone whether he can be the buyer in that building.
Don't carry an empty Long Beach house from your new city. Tony buys it. 1-908-768-4759.
§·· / Schedule
Tell Tony where the house is and what shape it's in. Get a cash number on the same call. Pick a closing date.
7 days a week, 8 AM to 9 PM Eastern.
Different situation? Tony also handles these Long Beach cases:
← All cash buyer options for Long Beach·Nassau County·New York