Can Tony buy my Hempstead house if foreclosure has already started?
Yes. Tony has stopped foreclosure sales 5 days before the auction date. The earlier you call, the more options exist — but Tony has closed deals at the eleventh hour too.
Most New York sellers in foreclosure don't know this: Tony's offer covers your full mortgage payoff at closing — and you often walk away with cash above what you owe. Tony has stopped Nassau County-area foreclosures days before the sheriff's sale.
If you're embarrassed to be in this situation, you shouldn't be. Tony has worked with hundreds of Hempstead-area homeowners facing foreclosure. You're not the first person to make this call, and you won't be the last. Tony doesn't judge, doesn't lecture, and doesn't waste your time.
If you're getting foreclosure notices from the bank or the Nassau County clerk, the worst thing you can do is wait. Most homeowners wait too long. Tony's been bringing Hempstead homeowners back from the edge of sheriff's sale for years. Cash buys you time, dignity, and in most cases a check above what you owe the bank.
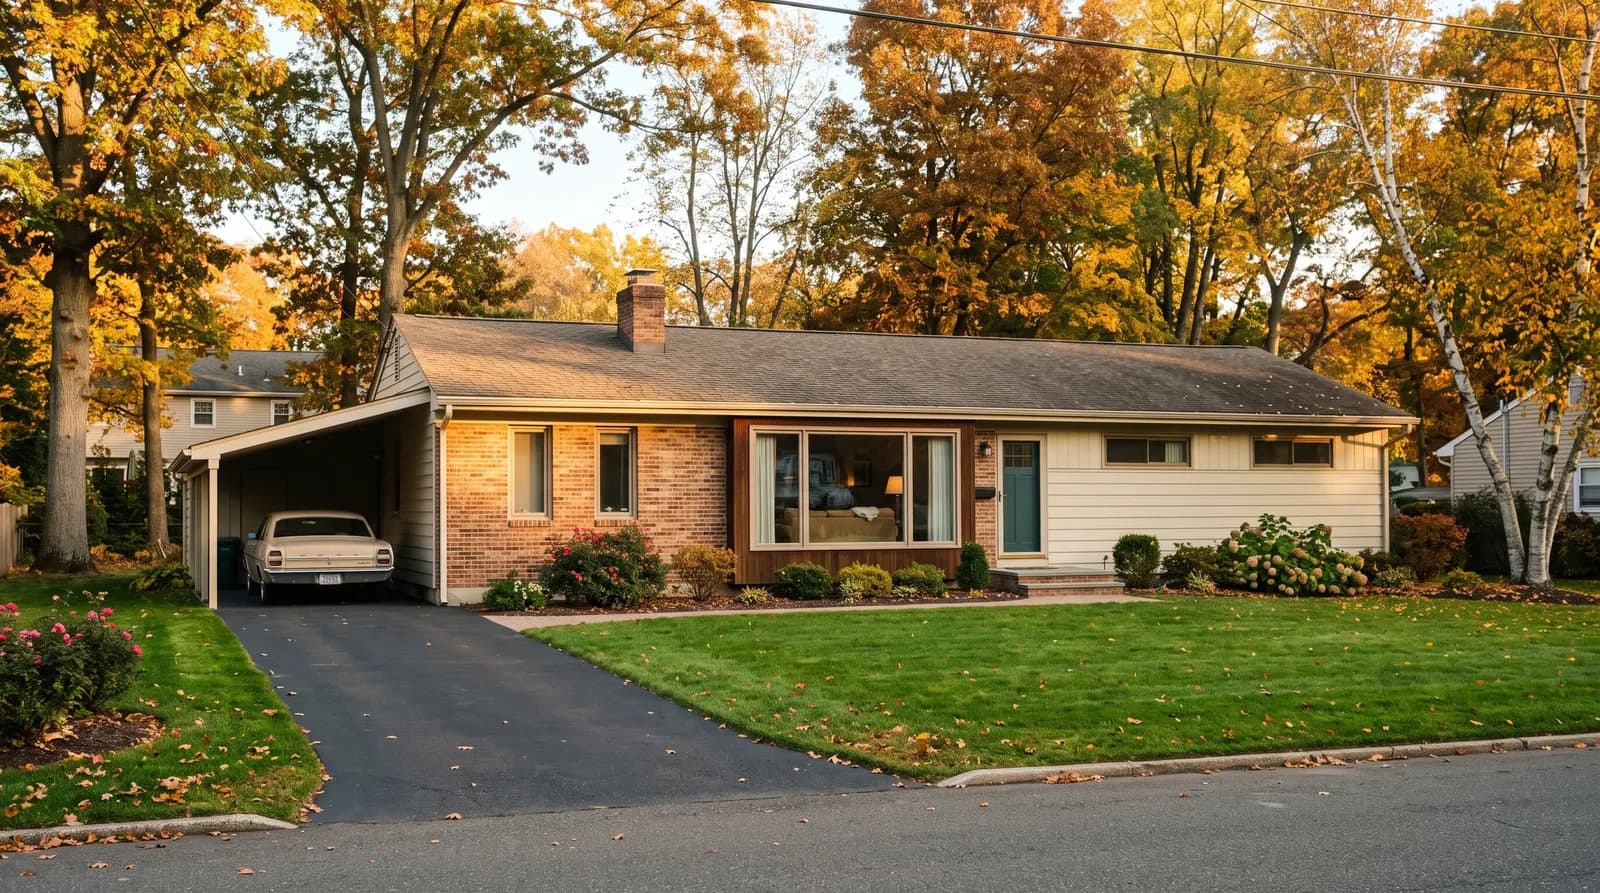
The kind of ranch property Tony has bought in Hempstead.
Nassau County is inner Long Island: Hempstead, North Hempstead, Oyster Bay. Levittown ranches, Long Beach co-ops, and Great Neck/Manhasset estates all part of Tony's Nassau pipeline.
Nassau County tax rates are 2.0-2.8%; assessment grievance is common given the elevated rates.
§·· / Schedule
Tell Tony where the house is and what shape it's in. Get a cash number on the same call. Pick a closing date.
7 days a week, 8 AM to 9 PM Eastern.
Tony has closed Nassau County foreclosure deals 5 days before the sheriff's sale. The sale gets canceled, the credit hit gets minimized, and you walk away with cash. Hempstead sellers in this situation say the same thing: they wish they'd called sooner.
Hempstead Town stretches across most of central Nassau. Tony buys capes, ranches, and splits in every village and unincorporated section. Hempstead Village itself is 1920s–40s frames and capes plus garden apartments and six-story buildings along Fulton and Front Streets; the surrounding hamlets — Uniondale, Roosevelt, East Meadow, Baldwin, Levittown — are 1950s capes, ranches, and splits on 60-by-100 lots, most with a dormer or extension added somewhere along the way.
Hempstead-area sellers call Tony after a parent's passing leaves a 1950s cape in Uniondale or Roosevelt with three heirs, a mortgage in default, and a finished basement the Town never permitted. Nassau's high taxes push out fixed-income seniors who can no longer carry $12,000 a year on a paid-off house, and the county's annual tax-lien sale turns one missed year into a compounding problem. Some owners are landlords with a Hempstead Village two-family in Nassau Landlord-Tenant court. Tony buys the cape with the illegal basement, the house in default, and the occupied two-family, and gives one number on the phone that closes on your date.
Hempstead sellers pay the 0.4% New York State transfer tax; on sales of $1 million or more the buyer pays the state mansion tax, which is Tony's cost. The usual Long Island closing snag is the Certificate of Occupancy: the Town of Hempstead Building Department must have records for every dormer, extension, deck, and finished basement, and a bank buyer will demand you legalize them — Tony buys "as-is C of O" for cash and takes that on himself. Deeds record with the Nassau County Clerk in Mineola, where Nassau Surrogate's Court also sits.
Every cash buyer, Tony included, starts from the same three numbers: what the house would sell for fully renovated, what it costs to get it there, and how long that takes. The offer is that finished value minus the repairs, minus the buyer's resale costs and margin. In practice that lands most cash offers somewhere around 70–85% of the renovated value, less repairs. The honest comparison is not against a renovated house's list price — it is against what you would actually net from a NY listing after commission, repairs, and months of carrying costs.
| Line item | List with an agent | Sell to Tony |
|---|---|---|
| What the house would sell for fully renovated | $400,000 | $400,000 |
| Repairs a retail buyer's lender will demand | − $45,000 | Tony's problem |
| Agent commission (5–6%) | − $20,000 to $24,000 | $0 |
| Inspection credits, seller closing costs, concessions | − $8,000 to $12,000 | $0 |
| Taxes, insurance, mortgage, utilities while you wait (3–6 months) | − $9,000 to $15,000 | $0 |
| Time to cash in hand | 4 to 7 months | 7 to 14 days |
| What you actually walk away with | ≈ $305,000 to $318,000 | Tony's number, in full, on your date |
Whether Tony's number beats that listing net depends on the house. On a move-in-ready home in a hot NYmarket it usually will not, and Tony will tell you to list. On a house that needs work, has tenants, sits in an estate, or carries violations — the houses retail buyers cannot finance — it is often close, and the seven-day timeline is the difference. Call 1-908-768-4759, get the number, and compare it yourself.
Buying since 2018· every county in New Jersey and New York · no commissions or fees · every closing at a licensed NY title company.
Contact
Drop your number and Tony reaches out about your Hempstead property within an hour.
Yes. Tony has stopped foreclosure sales 5 days before the auction date. The earlier you call, the more options exist — but Tony has closed deals at the eleventh hour too.
In most cases, yes — if your Hempstead house has any equity. Tony's offer pays off your mortgage and back taxes first, then the difference goes to you. On a typical NJ or NY property with 10-30% equity, that's $20,000-$80,000 in your pocket instead of vanishing into the foreclosure process.
Tony works with your lender on a short sale. Lenders often agree because Tony's deal is faster and more certain than waiting for sheriff's sale. You walk away with no continuing debt — much better than the foreclosure outcome.
The title company gets a payoff statement from your lender. At closing, Tony's wire goes to the title company; the title company sends your lender exactly what's owed and gives the rest to you. All same day.
Yes, significantly. A foreclosure stays on your credit for 7 years and triggers higher rates on future credit. Selling — even a short sale — has a much smaller credit impact and lets you start rebuilding immediately.
Yes — Hempstead Village (11550) and Uniondale, Roosevelt, West Hempstead, East Meadow, Baldwin, Freeport, Levittown, Elmont, Valley Stream, and every other village and hamlet in the Town. Capes, ranches, splits, colonials, two-families, and co-ops. One call with the address gets you a number.
Yes. Missing certificates of occupancy for extensions, dormers, decks, and basements are the single most common issue on Long Island houses, and Tony buys them as they are. A bank would make you legalize or remove the work before closing; Tony pays cash and deals with the Town of Hempstead Building Department after he owns it.
Yes. Whether the lien has been sold at Nassau's annual tax-lien sale or not, the arrears — plus any lienholder's interest — are paid off from the proceeds at closing. You don't need to catch up first. Tony's offer accounts for the payoff, and closing in about a week stops the interest from growing.
As soon as the court issues letters to the executor or administrator, Tony signs a contract and closes once title is clear — often within one to two weeks. Heirs out of state sign with a local notary and get wired. If the petition is still pending, Tony's attorney can tell you what the court needs, and the offer waits without expiring.
Every day matters now. Call 1-908-768-4759. Tony stops Nassau County foreclosures and pays you the difference.
§·· / Schedule
Tell Tony where the house is and what shape it's in. Get a cash number on the same call. Pick a closing date.
7 days a week, 8 AM to 9 PM Eastern.
Different situation? Tony also handles these Hempstead cases:
← All cash buyer options for Hempstead·Nassau County·New York