Will my lender approve a short sale on my West New York house?
Most do, especially when there's hardship documentation and a cash buyer ready to close. Tony's title company has worked with dozens of NJ and NY lenders and knows what each requires.
If you owe more on your Hudson County mortgage than the house is worth, Tony's short-sale process gets the lender to accept Tony's cash offer as full satisfaction. You walk away with no continuing debt. No deficiency. No long-term credit damage from foreclosure.
Being underwater on a house is one of the most demoralizing financial situations a homeowner can face. You're working to keep paying for something that's worth less than what you owe. Walking away feels like surrender, but staying feels like throwing money into a hole. A short sale is the cleanest exit — and Tony has done dozens of them across NJ and NY.
Hudson County short sales used to take 6-12 months. With Tony's experience and a motivated cash offer on the table, most close in 60-90 days. Faster than waiting for foreclosure, much cleaner than foreclosure on your credit.
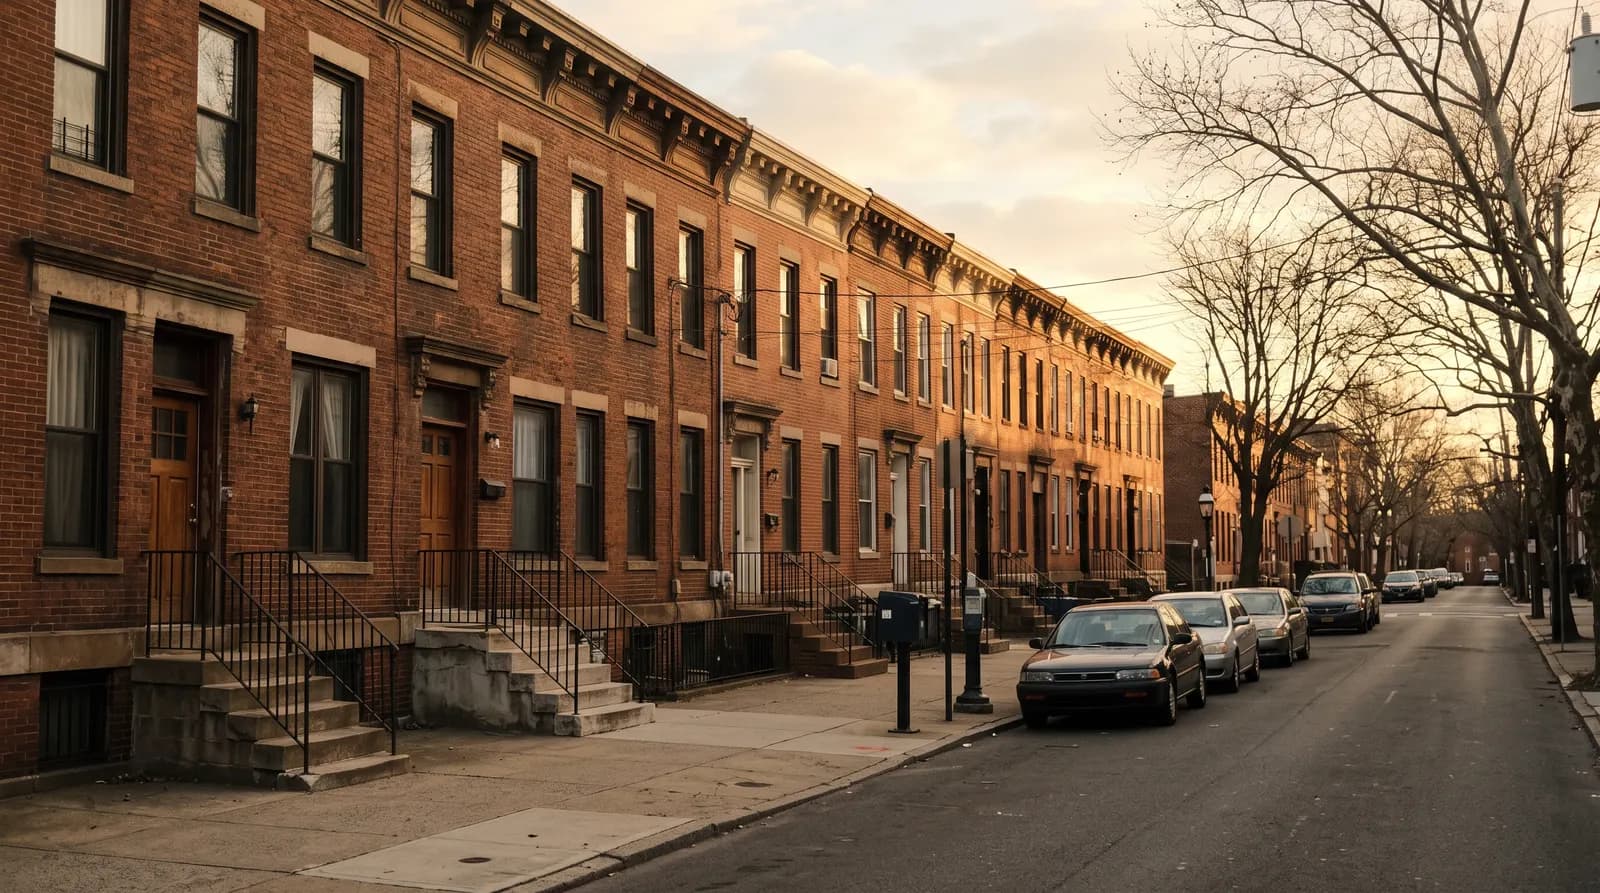
The kind of row house property Tony has bought in West New York.
Hudson County is dense urban: Jersey City brownstones, Bayonne row houses, Hoboken townhomes, North Bergen multi-families. Co-op and condo transactions are common.
Hudson County tax rates vary widely by municipality — 1.5% in Hoboken, 3.0% in Bayonne. Newer condo developments often have abated rates.
§·· / Schedule
Tell Tony where the house is and what shape it's in. Get a cash number on the same call. Pick a closing date.
7 days a week, 8 AM to 9 PM Eastern.
Here's how a Hudson County short sale works with Tony. Tony makes a cash offer. You sign a short-sale package authorizing Tony's title company to negotiate with your lender on your behalf. The lender reviews, approves the lower payoff, and the closing happens 60-90 days out. At closing, the lender accepts Tony's payment as full satisfaction; you have no remaining mortgage obligation.
West New York is one square mile of 1900s-1930s multi-families — frame three- and four-families with vinyl or asphalt siding, brick four- to eight-unit walk-ups, and mixed-use buildings along Bergenline with apartments over stores — plus a line of pre-war apartment buildings and newer condos on Boulevard East with the Manhattan view. Almost everything is tenant-occupied and under the town's rent control. Tony buys the walk-ups, the mixed-use buildings, and the condos.
West New York owners call Tony when a building has stopped paying for itself. A four-family the family bought in the 60s, now with three rent-controlled tenants and a fourth unit that has been vacant since the last inspection found the wiring. A landlord who has had enough of the rent leveling board, the state's lead-safe inspection requirement on pre-1978 units, and a CCO that keeps failing. Heirs who don't want to run a building in a town they left thirty years ago. And tax-sale certificates sold on buildings whose owners fell behind while dealing with all of the above. A listing means showings around eight households and a lender who wants every violation cleared first. Tony gives one number on the phone and closes on the seller's date.
West New York requires a Certificate of Continued Occupancy inspection before a resale, along with the fire department's smoke, carbon monoxide, and fire extinguisher certificate — Tony's side schedules both and buys with whatever the inspector writes up. The seller pays the NJ Realty Transfer Fee (about 1% on most sales, reduced for seniors and disabled owners on a principal residence). Leases, rent-control registrations, and security deposits transfer to Tony, and any tax-sale certificate or water lien is redeemed from proceeds at closing. No lender means no appraisal and no repair list.
Every cash buyer, Tony included, starts from the same three numbers: what the house would sell for fully renovated, what it costs to get it there, and how long that takes. The offer is that finished value minus the repairs, minus the buyer's resale costs and margin. In practice that lands most cash offers somewhere around 70–85% of the renovated value, less repairs. The honest comparison is not against a renovated house's list price — it is against what you would actually net from a NJ listing after commission, repairs, and months of carrying costs.
| Line item | List with an agent | Sell to Tony |
|---|---|---|
| What the house would sell for fully renovated | $400,000 | $400,000 |
| Repairs a retail buyer's lender will demand | − $45,000 | Tony's problem |
| Agent commission (5–6%) | − $20,000 to $24,000 | $0 |
| Inspection credits, seller closing costs, concessions | − $8,000 to $12,000 | $0 |
| Taxes, insurance, mortgage, utilities while you wait (3–6 months) | − $9,000 to $15,000 | $0 |
| Time to cash in hand | 4 to 7 months | 7 to 14 days |
| What you actually walk away with | ≈ $305,000 to $318,000 | Tony's number, in full, on your date |
Whether Tony's number beats that listing net depends on the house. On a move-in-ready home in a hot NJmarket it usually will not, and Tony will tell you to list. On a house that needs work, has tenants, sits in an estate, or carries violations — the houses retail buyers cannot finance — it is often close, and the seven-day timeline is the difference. Call 1-908-768-4759, get the number, and compare it yourself.
Buying since 2018· every county in New Jersey and New York · no commissions or fees · every closing at a licensed NJ title company.
Contact
Drop your number and Tony reaches out about your West New York property within an hour.
Most do, especially when there's hardship documentation and a cash buyer ready to close. Tony's title company has worked with dozens of NJ and NY lenders and knows what each requires.
60-90 days from offer to closing. The lender's review takes most of the time. Tony's part — the offer, the title work, the closing itself — moves fast.
The short-sale agreement typically includes a deficiency waiver, meaning the lender can't pursue you for the gap between what you owed and what they accepted. This is the single biggest difference vs. foreclosure.
Most lenders don't require it. Hardship documentation (job loss, medical, divorce, death) is usually enough. Earlier is better — you're in a stronger position if you haven't yet missed payments.
Less than foreclosure. Short sales typically drop credit 50-150 points and clear in 2-3 years. Foreclosure drops credit 200-400 points and stays 7 years. Major difference for getting another mortgage later.
Yes, with all of them in place. West New York's rent control follows the building, and Tony takes over as landlord at closing under the same leases and regulated rents. No buyouts, no notices, no waiting. Tell him how many units and what each actually pays and he'll quote one number for the building.
Yes. Store-plus-apartments buildings are a large part of West New York, and Tony buys them with the commercial and residential tenants in place, lease or no lease. He'll want to know what the store pays and how many apartments are above it, then he gives one number for the whole building.
Yes. A failed Certificate of Continued Occupancy blocks bank-financed buyers because the lender wants the corrections done before closing. Tony pays cash, buys as-is, and handles the CCO items after the sale. His number already accounts for that work — you don't repair anything or pay a contractor.
Yes. Tony buys individual condo and co-op units along Boulevard East and the waterfront in 07093, including units with a tenant in place, a special assessment coming, or maintenance arrears. Co-op boards add a step, which his attorney handles; there is still no bank and no appraisal.
Hudson County short sale specialist. 1-908-768-4759. Tony has done dozens.
§·· / Schedule
Tell Tony where the house is and what shape it's in. Get a cash number on the same call. Pick a closing date.
7 days a week, 8 AM to 9 PM Eastern.
Different situation? Tony also handles these West New York cases:
← All cash buyer options for West New York·Hudson County·New Jersey